
New 'Preston Bank' will have 'Captain Mainwaring-style' branch managers making lending decisions
The bank will be based in Preston and open its first branch in the city - but the council’s involvement has proved controversial.
Preston City Council has agreed to invest £750,000 in a new community bank which the authority’s leader says will boast individual branch managers who can build a “personal relationship” with their customers.
The decision, taken by the ruling Labour group at a recent full council meeting, means the city authority has now committed a total of £1m to support the launch of the North West Mutual.
The embryonic institution – which describes itself as an “ethical bank” – aims to improve access to finance exclusively for individuals and small or medium-sized businesses in the region after which it is named.
Councillors were told it will “combine modern digital banking with a regional branch network to ensure that local knowledge is embedded into lending and decision-making”.
City council leader Matthew Brown said the model would stand in contrast to the global banking system – and likened it to that portrayed in the 1970s comedy Dad’s Army, in which the character of Captain Mainwaring was a bowler-hatted wartime-era bank manager who dealt with customers directly.
However, opposition groups railed against the investment, branding the move a “high risk” duplication of well-established mutual building societies, which could easily result in the council’s cash being lost. They also claimed the money could be better spent on projects that would be of far more benefit to residents.
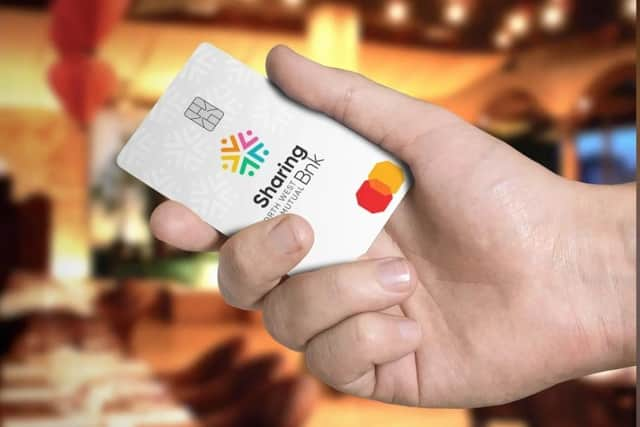

The North West Mutual has pledged to establish its headquarters in Preston and open its very first branch in the city in 2027 – with a total of 60 being planned across the wider region over the course of the next nine years.
The bank, which ultimately aims to serve 190,000 members, is currently working its way through the authorisation process for the establishment of new financial institutions.
Cabinet member for community wealth building Valerie Wise told the meeting at which the £750k was committed – in addition to £250k of shares purchased last year – that lending to small and medium-sized enterprises (SMEs) had halved within the last decade.
Of the 5,830 businesses based in Preston, 5,800 of them are SMEs – meaning they have fewer than 250 employees – a report to councillors said.
Cllr Wise said the majority of lending to SMEs was restricted to farms, buy-to-let landlords and care home owners, because they have “assets” against which the money can be secured.
“Very few other small and medium enterprises get lent money,” she said. “[The North West Mutual] will have a local branch manager who knows the local people, who knows the local economy and [whose decisions are not] just determined by some algorithm that doesn’t know exactly what the situation is.”
Making the Dad’s Army analogy – and reflecting on the banking of the mid-20th century – Cllr Brown said: “You actually had a bank manager who…[ran] the bank. You’d actually go in and meet the bank manager, you’d have a conversation with him, you’d…have a personal relationship.”
However, opposition parties lined up to pull the investment policy apart.
Liberal Democrat main opposition group leader John Potter said backing the North West Mutual was not going to “solve the inherent problems with British banking”, but amounted instead to “wasting Preston’s taxpayers’ money”.
“It says in black and white [in the report to council] this is a high risk adventure. [It is] very likely we will get zero back from this – and every penny we put in will be lost,” Cllr Potter warned.
He also noted that repayment of the borrowing for the investment would take the total cost closer to £2m – and asked Labour members, “What would you do with £2m in your wards?”
The city council has had £1m earmarked in its budget to invest in the new bank since back in 2019. Cllr Potter decried the fact that “in all that time”, the only other investor that had been secured was a “non-executive director” of the new institution. Liverpool City Council and Wirral Council previously walked away from plans to support the venture.
The North West Mutual will require £5m to enter what is known as the ‘authorisation with restrictions’ phase, whereby it will be given a banking licence, but can only accept a total of £50k deposits. A further £4m will be required to move beyond that stage and a total of £30m in capital will have to be raised in order to fund the bank’s full operation.
So far, the bank has secured ‘founder investment’ of £1m alongside the same amount committed by the city council. The report to councillors described the authority’s cash as being at “high risk” – should the Bank of England not grant the North West Mutual a licence or were it later to fail – because it was “initial investment funding”.
Lib Dem councillor Sean Little also questioned how the bank could give “preferential treatment in the decision to lend money” to a particular SME when the Financial Conduct Authority “govern[s] the lending criteria across the whole financial sector”.
Conservative group member Stephen Whittam said the bank proposal had “nothing to do with the core business of a council”.
“£750,000 [or] £2m, whatever it is, it’s a big sum that could be spent elsewhere – and it should be spent elsewhere,” Cllr Whittam said.
Reform UK councillor Stephen Thompson also criticised what he said was a “high-risk project to get involved in”.
However, deputy council leader – and cabinet member for resources – Martyn Rawlinson rubbished the comments coming from the other side of the chamber.
“There’s lots of things this council does that are high risk. Having an IT system is high risk – [but] we’ve got to have one.
“What you do is you mitigate those risks by managing it properly. And this bank is being set up properly by experts, so [the] risk is not high simply because of that,” Cllr Rawlinson said.
He also told the meeting that the potential £2m cost of the investment was just the way it had to be “shown on paper”.
“Unless we hand over a million [pounds] and it goes bust the day after – and we’ve lost all our money and there’s nowhere to go – it just won’t work out that way,” he said, accusing the Lib Dems of being a “hard right” party which was “ideologically opposed” to the bank in principle.
Meanwhile, Cllr Wise said the current dearth of investors could be explained by the fact that those who would be interested in committing to the project were awaiting the awarding of the restricted licence.
“They know then that it’s gone through all the regulatory requirements,” she explained.
Pay to play
The business case for the North West Mutual is based on personal current account holders paying a monthly £5 charge and businesses being charged a £10 monthly fee.
Liberal Democrat opposition group member Mark Jewell said that the set-up negated any “competitive advantage” the new bank might have.
Cllr Wise claimed that the interest paid on personal accounts would cover the charge, provided £1,000 per month was being paid in and there was an average of £250 in the account over that period. She said it might be possible to have “a lower fee or no fee” for those below a given income level, but that the business model submitted for consideration could not be changed at this point. She added that business account charges were commonplace.
However, Cllr Jewell said he could not “say or see what the benefits are” of the new institution.
“There are other mutuals already on our high street. I happen to know you…[have] the option of paying for accounts with certain benefits, but you do not have to pay to have an account with those building societies.
“And so when I…hear the arguments around that this is to help people who can’t normally get access to banks on particularly low income – however if you’ve got less than £1,000 a month you’ve got to pay £5 a month – that doesn’t add up to me at all,” said Cllr Jewell, who claimed the authority could “do so much more” with the money by further investing in the city’s parks.
Council leader Matthew Brown said the model was “based around some of the highly successful way[s] we do banking through co-operatives in Europe”.
“If you go back 20 years…when there was a financial crash and we were all told we couldn’t get our money out, it was not co-operative banks that were doing that, it was the large global banks – and we’ve seen [the] austerity that came from that,” Cllr Brown said.
How will the new bank work?
Once the North West Mutual has reached what it describes as ”adequate and sustainable profitability”, dividends will be paid out to its customers – or members – each of whom will have a vote in how the organisation is run.
In a statement on its website, the bank says that because it will be operating only in the North West, it will have a “drive and desire” to make the region “as financially strong and successful as it can be”.
The North West Mutual has previously told the Lancashire Post that it aims to recirculate £900m within the regional economy, which might otherwise have leaked out to other parts of the country.
“And so when I…hear the arguments around that this is to help people who can’t normally get access to banks on particularly low income – however if you’ve got less than £1,000 a month you’ve got to pay £5 a month – that doesn’t add up to me at all,” said Cllr Jewell, who claimed the authority could “do so much more” with the money by further investing in the city’s parks.
Council leader Matthew Brown said the model was “based around some of the highly successful way[s] we do banking through co-operatives in Europe”.
“If you go back 20 years…when there was a financial crash and we were all told we couldn’t get our money out, it was not co-operative banks that were doing that, it was the large global banks – and we’ve seen [the] austerity that came from that,” Cllr Brown said.